
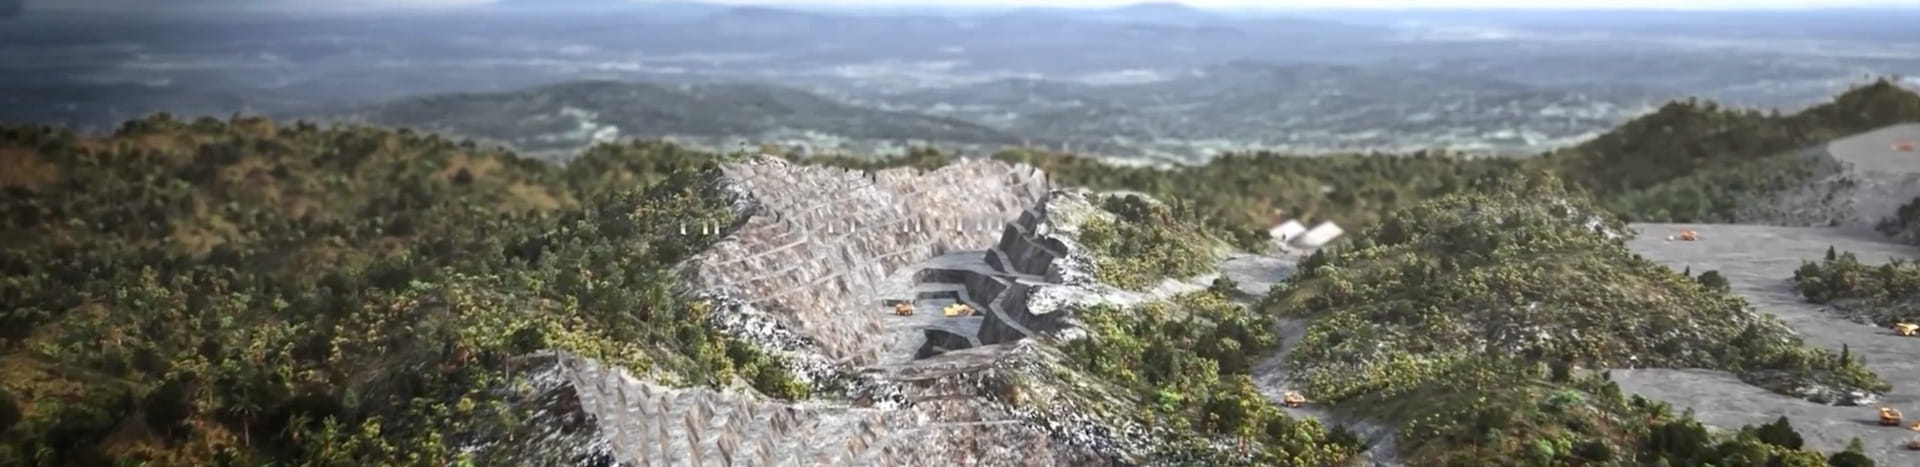
Mahenge Graphite Project
Black Rock Mining Ltd (ASX:BKT) has an 84% interest in the world-class Mahenge Graphite Project located in Tanzania which hosts a multi-generational graphite resource and is one of the largest JORC-compliant flake graphite resources globally, with 213m tonnes @ 7.8% TGC, and a reserve of 70m tonnes @ 8.5% TGC.
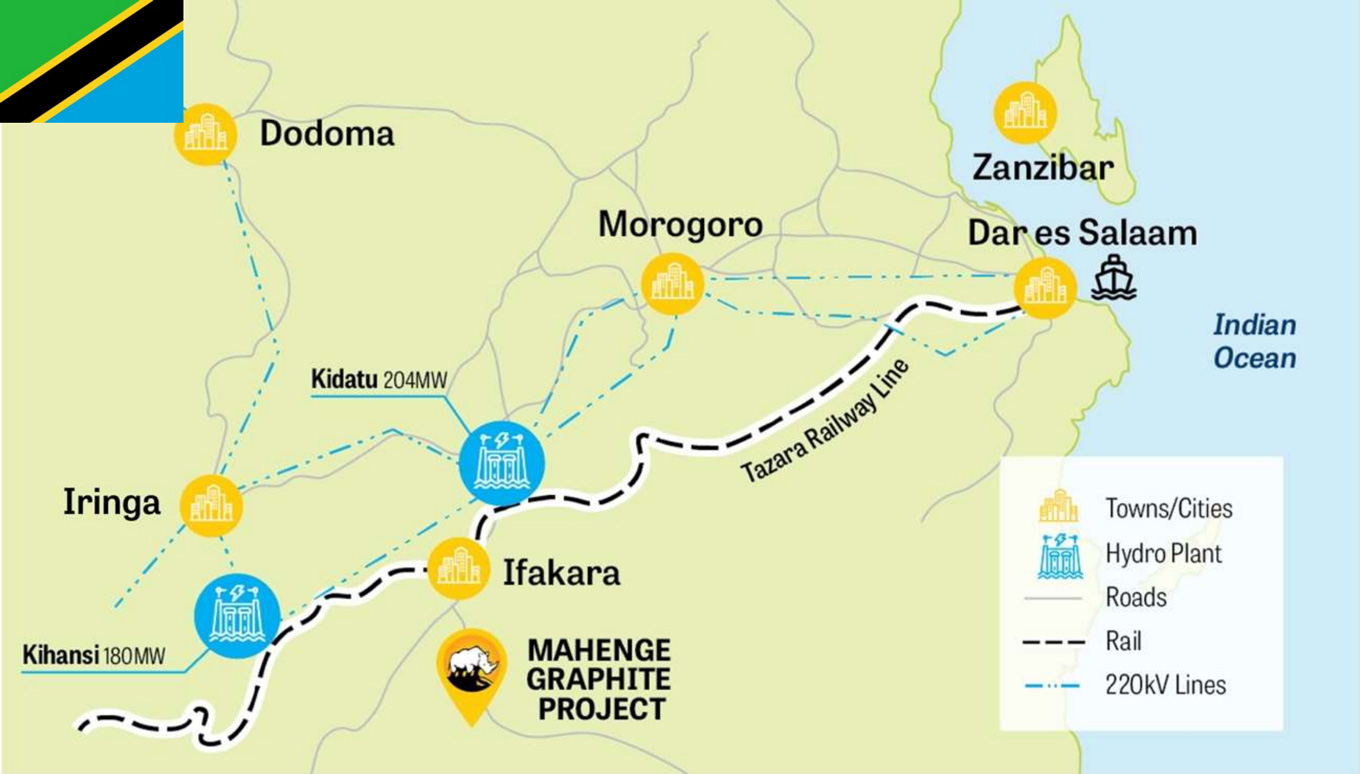
The Mahenge Graphite Project is located in south-eastern Tanzania, in the Ulanga District of the Morogoro Region, approximately 350 km southwest of Tanzania’s largest city Dar es Salaam and 70 km south of the town of Ifakara. The distance by road from Dar es Salaam to the site is approximately 482 km. The nearest town is the Mahenge township, located approximately 9 km from the site.

Black Rock’s Definitive Feasibility Study for the Project considers a four-stage construction schedule to deliver up to 340,000 tonnes per annum of 98.5% graphite concentrate for 26 years of 98.5% LOI premium graphite flake concentrate with the ability to produce Ultra Purity flake of 99% LOI.

The Mahenge Graphite Project brings together scale, product quality and strategic partnerships in a staged development to deliver Naturally Better Graphite
First Quartile Costs: Forecast sustained competitiveness
Infrastructure and location drive long term competitiveness
Geography: Costs
- Hydro-dominated grid power
- Deep-water ports
Geography: Revenue
- Geological advantages with more higher value large flake graphite with purity
Partners
- Crawl, walk, run
- 4 stage self funding modular strategy
95% TGC & 97.5% TGC for the Mahenge Graphite Project (Adjusted ASIC US$ 313*)

Sources: Benchmark Mineral Intelligence Flake Graphite Report Q4 CY25, Black Rock Mining, Company Data
C1 Cash Costs are defined as Cash Costs excluding royalties and sustaining capex.
* Cost curves normalized for 94-95% TGC, 90% passing #100 mesh. Curve adjusted by assuming Mahenge Graphite Project concentrate grade premium of 10% for -100# grade shipped at 96% TGC and 25% for all other products shipped at 97.5% TGC. All pricing FOB Dar excluding discounts.
Refer to Black Rock ASX release dated 10 October 2022, Black Rock completes FEED and eDFS Update for further details on the key Project assumptions and risks.
Scale
Global #2 JORC Reserve
150% sector growth over next decade
Long life intergenerational asset
Products
In demand >95% contracted
Differentiated – Low impurity & large flake
Projected >3:1 revenue to normalised AISC cost
Partners
Risk mitigation
Framework & licences in place
Disciplined “Crawl, Walk, Run” execution model
Dry stack, community engagement – sustained ESG advantage